My Safe Florida Home Funding Status: Where the 2026-2027 Cycle Stands
The 2026-2027 status of My Safe Florida Home: the portal is open, $378.3 million carried forward under HB 5001-E, and what history says about how fast it moves.
The 2026-2027 status of My Safe Florida Home: the portal is open, $378.3 million carried forward under HB 5001-E, and what history says about how fast it moves.
The buyer's insurance quote runs on a wind mitigation form that names every opening. The pre-listing audit, warranty transfer deadlines, and disclosure rules.
My Safe Florida Home no longer keeps an approved contractor list. Who can legally do the work, what the program checks, and who fronts the money under the grant.
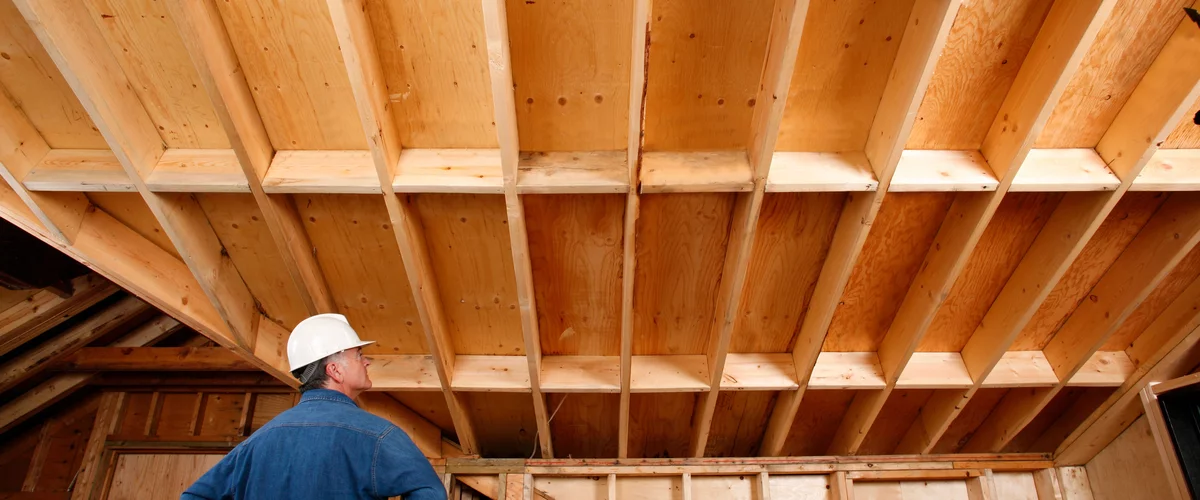
Florida insurers ask for two different inspections. The 4-point decides insurability; the wind mitigation earns credits. Who needs which, and what each costs.
What a wind mitigation inspection costs in Florida, what changes the price, and the two legitimate ways to get the OIR-B1-1802 report free or reimbursed.
What the Florida garage door wind code actually requires: design pressure ratings by region, DASMA 108 and 115 testing, HVHZ impact rules, label reading, permits, and how the door affects your insurance credit.
There is no federal window tax credit for 2026 installs. Florida's replacement is a one-time sales-tax refund of up to $500 per homesteaded home for impact windows, doors, and garage doors, claimed from the Department of Revenue after installation.
The OIR-B1-1802 wind mitigation form decides your Florida hurricane insurance discount, often $300 to $3,500 a year. Here is what it checks and what changed in the new April 2026 version.
To harden a Florida home against hurricane damage on a real budget, sequence the upgrades over four or five seasons. Roof first, openings second, garage door, generator, yard.
Florida hurricane insurance is actually three separate products. Most homeowners only learn the difference after a storm. Here is the plain-English breakdown.